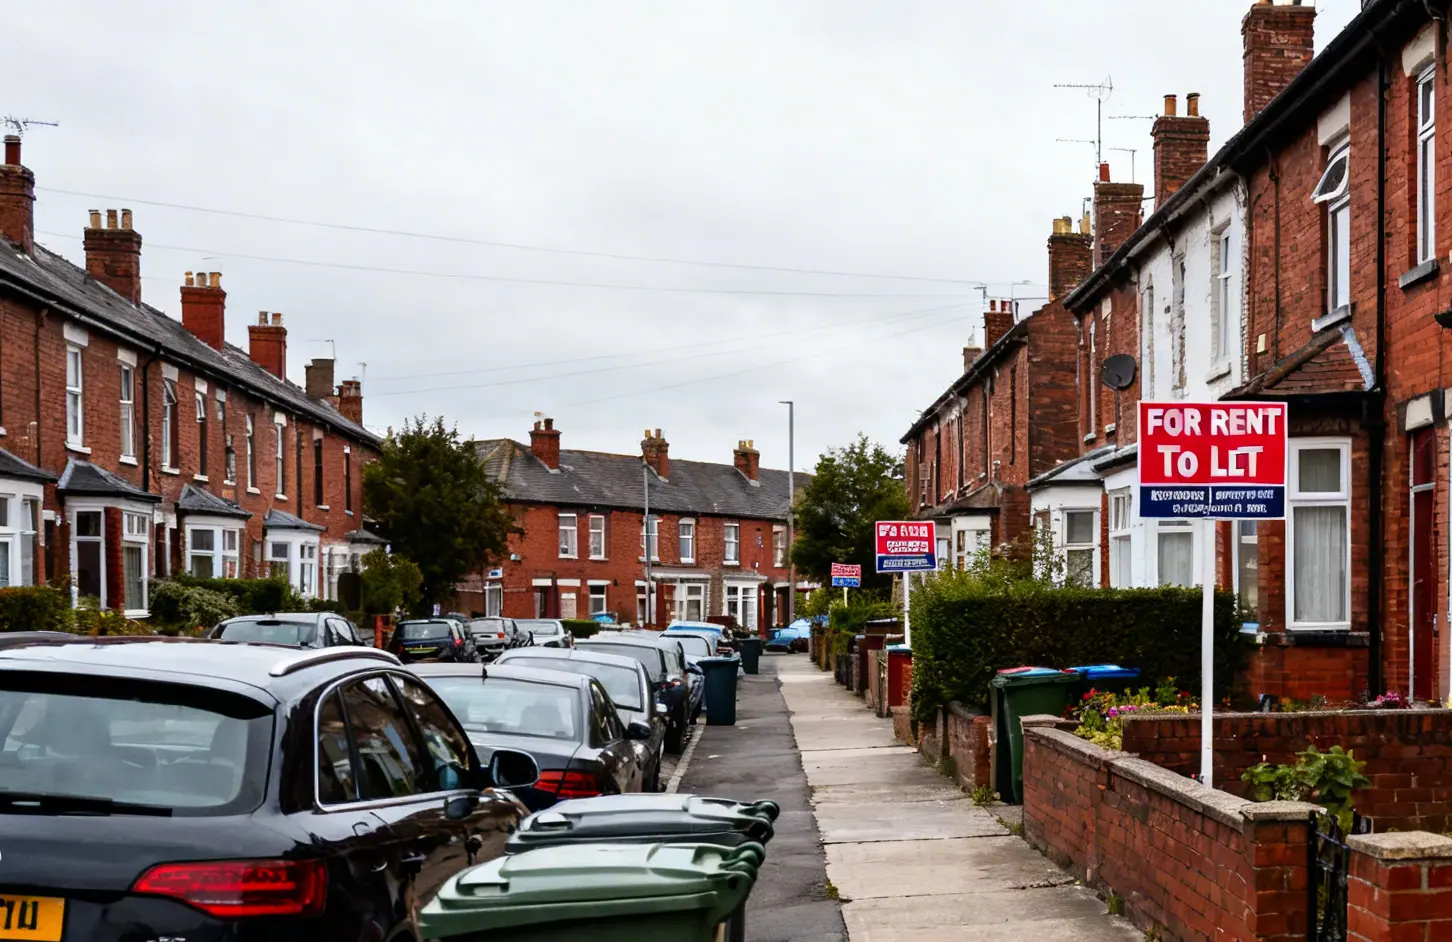
Tenancy fraud has emerged as a £4.6 billion annual drain on UK landlords, representing one of the most significant yet underreported threats to rental sector profitability. The scale of criminality targeting private landlords now surpasses the annual yield from commercial property investments across entire regional markets, with 275,000 property owners having suffered direct financial losses according to industry analysis. This epidemic of rental fraud - costing an estimated £380 million monthly - has reached proportions that dwarf traditional concerns about void periods or maintenance costs, fundamentally altering the risk profile of buy-to-let investment.
The mechanics of this fraud wave centre overwhelmingly on rent default, which accounts for 70% of reported cases, but the sophistication has evolved far beyond simple non-payment. Professional fraud rings now deploy fake employment references, forged bank statements, and identity theft to secure high-value tenancies before disappearing with deposits and months of unpaid rent. In Manchester and Birmingham, where rental yields traditionally attract yield-hungry investors, landlords report increasingly elaborate schemes involving multiple properties and coordinated teams of fraudsters. The financial impact extends beyond immediate losses: properties tied up in legal proceedings can remain void for 6-12 months, compounding the damage through lost rental income and mounting legal costs.
The inability of 70% of affected landlords to recover their losses exposes critical weaknesses in both the legal framework and insurance provision underpinning the rental sector. Unlike commercial property fraud, which benefits from sophisticated due diligence processes and comprehensive insurance coverage, residential lettings remain vulnerable to exploitation through outdated reference checking systems and inadequate legal recourse. In London and Surrey, where average monthly rents exceed £2,500, a single sophisticated fraud can inflict losses equivalent to 18 months of rental income when legal costs and void periods are factored in. This reality is driving fundamental changes in landlord behaviour, with increasing numbers requiring guarantors earning 2.5x annual rent and demanding six months' rent in advance.
Regional markets are experiencing divergent impacts based on local rental dynamics and fraud patterns. In Newcastle and Leeds, where lower rental values might suggest reduced fraud appeal, landlords actually report higher incident rates due to less stringent vetting procedures and greater reliance on local letting agents with limited fraud detection capabilities. Conversely, Liverpool's rental market has seen organised fraud targeting student accommodation, with fake overseas student applications becoming increasingly prevalent as international student numbers recover post-pandemic. These regional variations are creating a two-tier market where fraud-aware landlords concentrate investments in areas with stronger legal enforcement and professional property management infrastructure.
The £380 million monthly loss figure represents approximately 3.2% of total monthly rental income across the UK private rental sector, effectively functioning as an invisible tax on legitimate rental provision. This burden inevitably feeds through to rental pricing, with landlords increasingly factoring fraud risk into rental assessments alongside traditional costs like mortgage payments and maintenance. For buy-to-let investors operating on typical net yields of 4-6%, fraud losses of this magnitude can eliminate annual profitability entirely. The situation has prompted major rental insurance providers to exclude fraud coverage or impose prohibitive excess levels, further concentrating risk on individual landlords rather than distributing it across the insurance market.
Looking ahead 12 months, the trajectory points toward fundamental structural changes in how the rental sector operates. Technology solutions including blockchain-verified references and real-time income verification are gaining traction among professional landlords, while the amateur buy-to-let sector faces increasing pressure to professionalise or exit the market entirely. Major institutional investors, who have largely avoided these fraud losses through sophisticated vetting procedures, are positioned to benefit from any exodus of smaller landlords unable to absorb ongoing fraud risks. The government's proposed rental sector reforms, including mandatory property portals and enhanced tenant identification requirements, may provide some relief but implementation timelines extend well into 2025.
The scale of tenancy fraud now represents an existential threat to the viability of small-scale buy-to-let investment in the UK. Combined with existing pressures from tax changes, mortgage rate increases, and regulatory compliance costs, fraud losses are accelerating market consolidation toward professional operators with sophisticated risk management capabilities. For the 2.7 million UK landlords, the choice increasingly becomes: invest heavily in fraud prevention technology and professional management, or accept that rental property investment has fundamentally changed from a passive income stream to an active business requiring constant vigilance and substantial reserves.
Key Takeaways
- Tenancy fraud costs UK landlords £4.6bn annually, with 70% of the 275,000 affected unable to recover losses
- Rent default accounts for 70% of cases, but sophisticated fraud rings now use fake documents and identity theft
- Regional markets show varying vulnerability, with student areas and lower-value markets experiencing higher incident rates
- The crisis is accelerating market consolidation toward professional landlords with advanced fraud prevention capabilities


