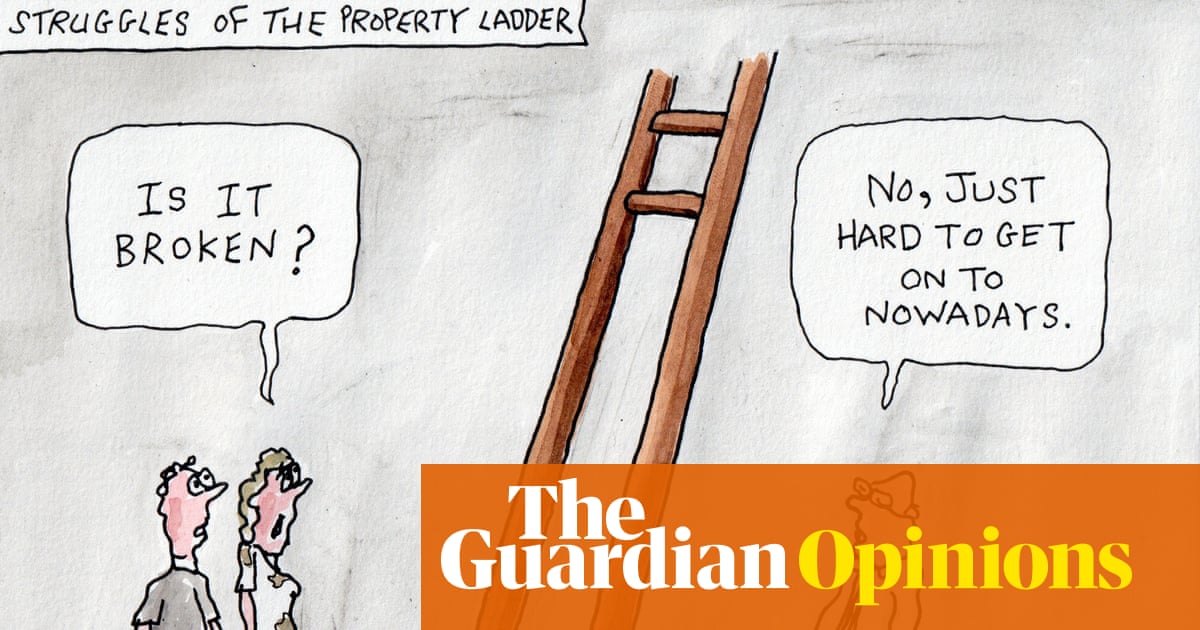
UK house sales stayed flat last month, according to the latest transaction data, with estate agents and analysts pointing to underlying 'resilience' rather than weakness as the defining feature of the market. On the surface, a stagnant month might look like a warning sign. But for anyone tracking the sector closely, the more interesting story is what hasn't happened: no collapse in demand, no disorderly price correction, and no mass retreat of buyers despite a punishing few years of higher borrowing costs and a reshaped stamp duty regime.
Context matters enormously here. Transaction volumes have been volatile since the stamp duty thresholds reverted in April, pulling forward a wave of completions earlier in the year as buyers rushed to beat the deadline. That distortion has made month-on-month comparisons unusually noisy, and a flat reading now likely reflects a market settling back into a more normal rhythm rather than genuine stagnation. HMRC figures earlier this year showed transactions swinging by more than 25% month-on-month around the deadline, so a period of consolidation was always the probable next chapter, not a red flag.
For buy-to-let landlords, this steadiness is arguably good news. A market that isn't lurching between boom and bust offers more predictable conditions for underwriting yields, particularly in regional hubs like Manchester, Leeds and Birmingham, where rental demand remains structurally strong and gross yields continue to outperform London by two to three percentage points. Landlords in these cities have spent the past 18 months absorbing higher mortgage costs and tighter regulation; a flat but stable transactions market suggests asset values won't erode further in the near term, giving landlords room to plan refinancing and portfolio expansion with more confidence than they've had since 2022.
First-time buyers face a more mixed picture. Mortgage rates have eased modestly from their 2023 peaks, with average two-year fixed rates now hovering in the mid-4% range compared with highs above 6%, but affordability remains stretched, particularly in the South East and Surrey's commuter-belt towns, where average prices still sit well above £450,000. Northern cities continue to offer the more compelling entry point: Liverpool and Newcastle remain among the few major markets where average prices sit below £200,000, and it's in these areas that transaction volumes have held up best, reinforcing a broader north-south divergence in market momentum that has become one of the defining features of the post-pandemic property landscape.
Commercial investors and developers should read the flat sales data as a signal to focus on fundamentals rather than momentum. With transaction activity plateauing, pricing power is shifting subtly back towards buyers in slower-moving segments, while well-located, well-specified stock — particularly new-build homes near transport infrastructure in Manchester and Birmingham's regeneration zones — continues to command premiums and sell relatively briskly. Developers who over-extended during the low-rate era face a tougher financing environment, but those with strong balance sheets are finding opportunities to acquire stalled sites at more realistic valuations, setting up a favourable position for when transaction volumes eventually reaccelerate.
Looking ahead six to twelve months, expect transaction volumes to grind higher rather than surge, supported by anticipated Bank of England rate cuts and gradually improving real wage growth. Any further reduction in the base rate towards 3.75% by mid-2026 would meaningfully improve affordability calculations for first-time buyers and could unlock pent-up demand that has been suppressed rather than destroyed. Regional markets in the North and Midlands look best positioned to benefit first, given their lower price bases and stronger yield profiles, while London and the South East will likely see a slower, more grinding recovery given stretched affordability ratios that remain among the highest in Europe relative to average earnings.
The takeaway for investors is that flat data this month should not be mistaken for a market losing momentum. It is a market absorbing a major fiscal shock, digesting higher borrowing costs, and rebalancing around a new, lower-transaction equilibrium that is nonetheless structurally sound. Those who mistake stability for stagnation risk missing the entry point before the next phase of regional price growth begins.
Key Takeaways
- Flat transaction figures reflect post-stamp duty deadline normalisation rather than a genuine demand slump
- Northern cities including Manchester, Liverpool and Newcastle continue to outperform on both yield and transaction resilience versus London and Surrey
- Buy-to-let landlords benefit from reduced volatility, offering clearer conditions for refinancing and portfolio planning
- Expect gradual, rate-cut-driven improvement in transaction volumes over the next 6–12 months, with regional markets leading any recovery