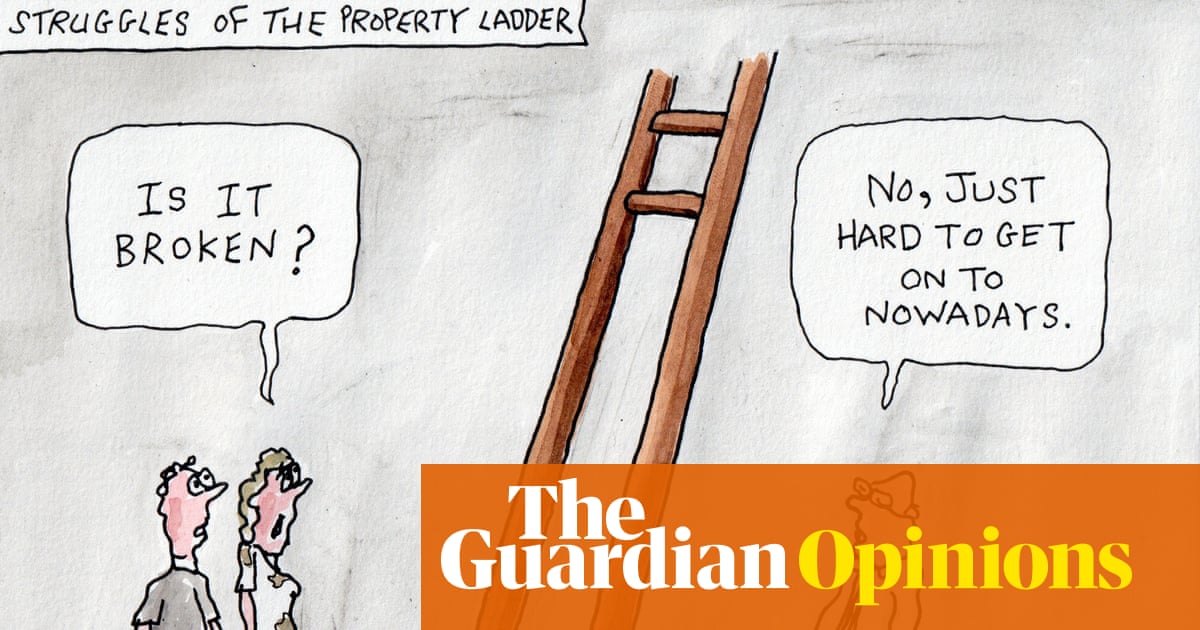
This week's Guardian cartoon by Stephen Ashman, skewering the impossible arithmetic facing first-time buyers, lands at a moment when the joke is uncomfortably close to the balance sheet reality for millions of prospective homeowners. The satire is pointed precisely because it is accurate: the average first-time buyer deposit in England now sits above £61,000, according to Halifax data, while in London that figure exceeds £120,000. For a generation earning median full-time salaries of roughly £35,000, saving that sum while paying rent that consumes 30-40% of take-home pay is not a temporary inconvenience — it is a structural barrier that cartoons capture more efficiently than any government white paper.
Why does this matter beyond the human interest angle? Because the first-time buyer is the engine that keeps the entire housing chain moving. Every stalled first purchase delays a chain of sales further up the ladder, from the young family upgrading to a three-bed semi to the retiree downsizing from a five-bedroom house in Surrey. Estate agents report that transaction volumes in England and Wales remain roughly 15-18% below pre-2016 averages, and much of that shortfall traces directly to first-time buyers being priced out or mortgage-restricted. For investors and developers, a housing market with a constricted entry point is a market with reduced liquidity throughout, which suppresses transaction-driven revenue for agents, conveyancers, and — critically — build-to-sell developers who rely on first-time buyer demand to absorb new-build stock.
The regional picture is stark and instructive for anyone allocating capital. In London and Surrey, average first-time buyer prices now exceed £430,000 and £380,000 respectively, pushing average age of first purchase towards 34-36. Contrast this with Manchester, where first-time buyers can still find flats and terraces around £180,000-£210,000, or Newcastle, where sub-£150,000 entry points remain common in outer boroughs. Liverpool and parts of Birmingham offer similar affordability, which explains why these cities have seen disproportionate growth in first-time buyer mortgage approvals over the past two years — up an estimated 12% in the North West against a national average closer to 4%. Leeds sits in between, benefiting from strong graduate retention and a growing professional services sector that supports demand without London-level pricing.
Mortgage rates compound the deposit problem rather than easing it. With average two-year fixed rates hovering around 4.6-5.1% for higher loan-to-value products, monthly repayments on a typical first-time buyer mortgage have risen by roughly £250-£300 compared with the ultra-low-rate era of 2021. Lenders have responded with product innovation — extended terms of 35-40 years, and a modest revival of sub-10% deposit products — but these are palliatives, not cures. Longer terms reduce monthly outgoings while dramatically increasing total interest paid, effectively transferring cost from the point of purchase to a borrower's entire working life. This is precisely the kind of structural trade-off that satire is well-placed to expose and that policy discussion too often glosses over.
For buy-to-let landlords, the frozen first-time buyer market is a mixed blessing. On one hand, would-be buyers who cannot purchase remain tenants for longer, sustaining rental demand and supporting the 5-7% annual rental growth seen in major regional cities over the past 18 months. On the other, this dynamic invites political scrutiny and potential intervention — from stamp duty reform to renewed talk of rent controls — as governments face pressure to visibly address the affordability crisis. Commercial investors eyeing purpose-built rental schemes (PBSA-adjacent build-to-rent developments) should treat the first-time buyer squeeze as a durable demand signal for professionally managed rental stock in cities like Manchester, Leeds and Birmingham, where institutional capital has already committed billions to large-scale rental developments precisely because homeownership timelines are stretching.
Looking to the next six to twelve months, expect three concrete developments. First, continued political pressure will likely produce incremental first-time buyer support — an extended or reformed Lifetime ISA, modified stamp duty thresholds, or expanded mortgage guarantee schemes — none of which will fundamentally alter the deposit-to-income ratio but will marginally accelerate transaction volumes. Second, regional divergence will widen further: expect first-time buyer activity in the North West and North East to outpace the South East by a factor of two to three, reinforcing the case for developers to weight new-build pipelines toward these markets. Third, if the Bank of England delivers the widely anticipated rate cuts through 2026, expect a modest thaw in first-time buyer mortgage approvals — perhaps 6-8% growth — though this will be offset by continued house price inflation in undersupplied cities, keeping the fundamental affordability equation largely unchanged.
The cartoon's power lies in reducing a complex market failure to a single, devastating image. The underlying data confirms what the satire implies: this is not a cyclical dip correctable by modest rate cuts or one-off government schemes, but a structural mismatch between wages, housing supply and financing costs that has been building for over a decade. Investors and developers who recognise this as a durable regional and demographic shift — rather than a temporary market wobble — will be better positioned to allocate capital toward the rental and affordable-ownership products that this generation of buyers actually needs.


