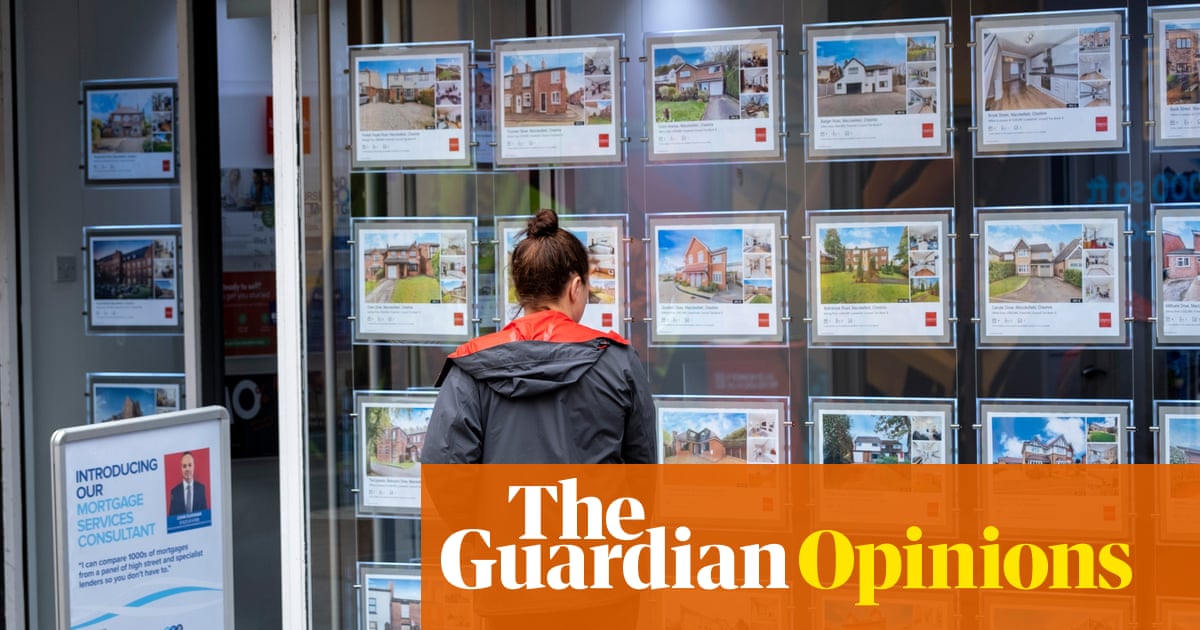
Landlords across the UK face a fresh blow to their returns after the Autumn Budget 2026 confirmed a 4% increase in income tax on rental earnings, due to take effect from 2027, as Mortgage Strategy reported. The announcement marks another significant intervention in a private rented sector that has already absorbed years of tax and regulatory change, and it will force landlords, letting agents and mortgage brokers to reassess the viability of buy-to-let portfolios well before the measure comes into force.
For professional investors, the timing and direction of this policy matter more than the headline figure alone. The private rented sector has long been treated by successive governments as a source of additional revenue, from the removal of mortgage interest relief to stamp duty surcharges on additional properties. A further 4% rise in income tax on rental income continues that trajectory, reinforcing a pattern in which landlords are increasingly viewed as a tax base rather than a protected investor class. For landlords operating on tight margins, particularly those with mortgaged properties rather than outright ownership, this is not a marginal adjustment but a direct hit to net yield.
The practical effect will vary significantly depending on how landlords are structured and where their properties are located. Investors holding portfolios through limited companies may find themselves partially insulated, since the tax change applies to income tax rather than corporation tax, a distinction that is likely to accelerate the long-running shift from personal ownership to incorporated structures. Landlords in cities with historically strong rental demand, such as Manchester, Birmingham, Leeds and London, may be better placed to pass on some of the cost through rents, given sustained tenant demand in these markets. By contrast, landlords in areas with softer rental growth or higher void periods, potentially including parts of Liverpool and Newcastle, will have less room to adjust and may see compressed returns rather than higher rents.
The announcement also raises the prospect of further landlord exits from the sector. A 4% income tax increase, layered onto existing costs such as higher mortgage rates and compliance obligations under evolving regulation, is likely to tip the calculations for landlords already weighing whether to sell. PropertyNews analysis suggests that smaller, individual landlords with one or two properties are the most exposed, since they typically lack the scale to absorb additional tax through portfolio-wide efficiencies that larger or incorporated investors can access. If this group continues to retreat from the market, as has been the trend in recent years, the long-term effect could be a further tightening of rental stock in cities where demand is already outstripping supply.
For first-time buyers, the implications are more ambiguous than they might initially appear. A reduction in landlord activity could, in theory, free up more properties for owner-occupiers, particularly at the lower end of the market where investors and first-time buyers often compete directly. However, if landlords respond by raising rents rather than selling, tenants seeking to save for a deposit could find it harder to accumulate capital, delaying their transition from renting to ownership. Commercial investors and developers, meanwhile, are likely to watch this measure closely as a signal of broader government intent towards property taxation, with potential read-across to build-to-rent and institutional investment strategies if sentiment towards private landlords continues to deteriorate.
Looking ahead to the next six to twelve months, the property market should expect a period of recalibration rather than immediate upheaval, given the 2027 implementation date provides landlords with a window to plan. Expect increased activity around incorporation, portfolio restructuring and early disposals from landlords seeking to exit before the change takes hold. Mortgage brokers and letting agents will play a critical advisory role during this transition, helping clients model the after-tax impact on different ownership structures. The clearest conclusion for investors is that the economics of buy-to-let in its traditional personal-ownership form are becoming progressively less attractive, and those who adapt their structures early are likely to be best positioned when the change takes effect in 2027.