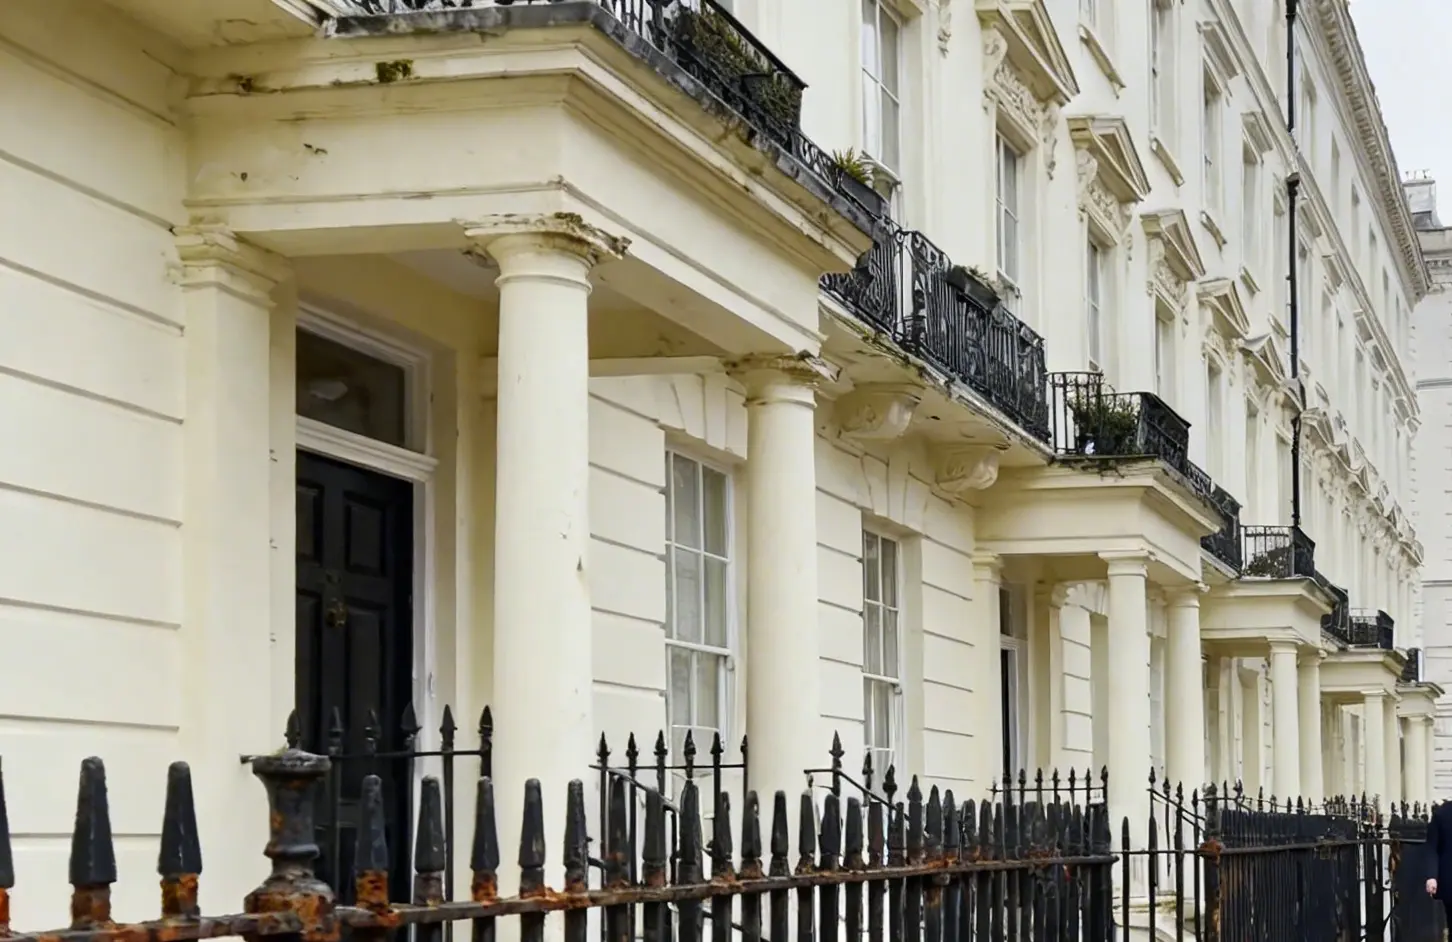
Prime central London property values have plunged by as much as 25% in recent months, marking the most significant correction in the capital's luxury residential sector since the 2008 financial crisis. The decline represents a fundamental shift in market dynamics that will reverberate across the UK's broader property landscape, particularly as international investors reassess their exposure to sterling-denominated assets amid persistent economic headwinds and elevated interest rates.
The absence of distressed selling despite such dramatic price falls reveals the unique characteristics of London's ultra-prime market, where cash-rich vendors can afford to withdraw properties rather than accept reduced valuations. This phenomenon has created an increasingly illiquid market where transaction volumes have collapsed by an estimated 40-50% compared to historical averages. Properties in Mayfair, Belgravia, and Knightsbridge - traditional bastions of international wealth - are experiencing the steepest declines, with some developments seeing asking prices reduced from £3,000 per square foot to below £2,250 per square foot.
The correction fundamentally alters investment calculations for UK property markets beyond the capital. Regional prime markets in Surrey's stockbroker belt, where values often track London trends with a six-month lag, face inevitable downward pressure as wealthy buyers redirect attention to suddenly affordable central London opportunities. Manchester and Birmingham's luxury apartment sectors, which have attracted London-priced capital in recent years, may see investment flows reverse as £5 million now secures prime Marylebone properties that commanded £6.5 million eighteen months ago.
For institutional investors and family offices, the pricing reset creates the most compelling London entry point since 2009, though liquidity constraints mean deployment must be patient and strategic. The constrained supply environment - with many developers delaying launches and existing owners refusing to crystallise losses - suggests that when market confidence returns, price recovery could prove swift and substantial. International buyers from the Middle East and Asia, deterred by previous peak pricing, are beginning preliminary market reconnaissance as sterling weakness amplifies the effective discount.
Buy-to-let investors operating in London's prime rental market face a complex recalibration. Rental yields in central London have improved from historically compressed levels of 2-2.5% to potentially attractive 3.5-4% as purchase prices fall while rental demand from international executives and students remains robust. However, elevated borrowing costs mean leveraged investors still face challenging returns, particularly as estate agents report tenants increasingly negotiating rental reductions in properties priced above £1,000 per week.
The broader implications extend to UK regional markets where London wealth has historically driven secondary home purchases and retirement relocations. Cities like Bath, Oxford, and Edinburgh may experience reduced investment pressure as London's wealthy classes focus on securing discounted prime central properties rather than diversifying geographically. This dynamic could provide first-time buyers in these markets with improved affordability, though mortgage accessibility remains constrained by lending criteria tightened in response to recent economic volatility.
Market recovery depends critically on macroeconomic stabilisation and clarity over future tax policy, particularly regarding non-dom status and capital gains treatment. The current correction represents a necessary reset that eliminates speculative froth while preserving London's fundamental appeal to international capital. With construction costs remaining elevated and planning constraints unchanged, supply limitations will ultimately support price recovery once confidence returns, making current conditions a defining opportunity for well-capitalised investors prepared to take a three-to-five-year view on London's luxury residential market.
Key Takeaways
- Prime central London prices down 25% but lack of distressed sales indicates market floor forming around current levels
- Transaction volumes collapsed 40-50% creating illiquid market with constrained supply supporting future price recovery potential
- Regional prime markets face downward pressure as investors redirect to suddenly affordable central London opportunities
- Rental yields improved to 3.5-4% range creating opportunities for cash buyers despite challenging returns for leveraged investors


