The buy-to-let investment landscape has undergone a fundamental transformation, with the traditional dominance of southern England decisively broken by a sustained northern surge. UK Finance data reveals that the South's share of mortgaged buy-to-let purchases has plummeted from 56% in 2015 to just 38% in 2025, marking the most significant geographical redistribution of rental investment capital in modern property history. This 18-percentage-point swing represents billions of pounds in redirected investment, fundamentally altering the rental market dynamics across Britain.
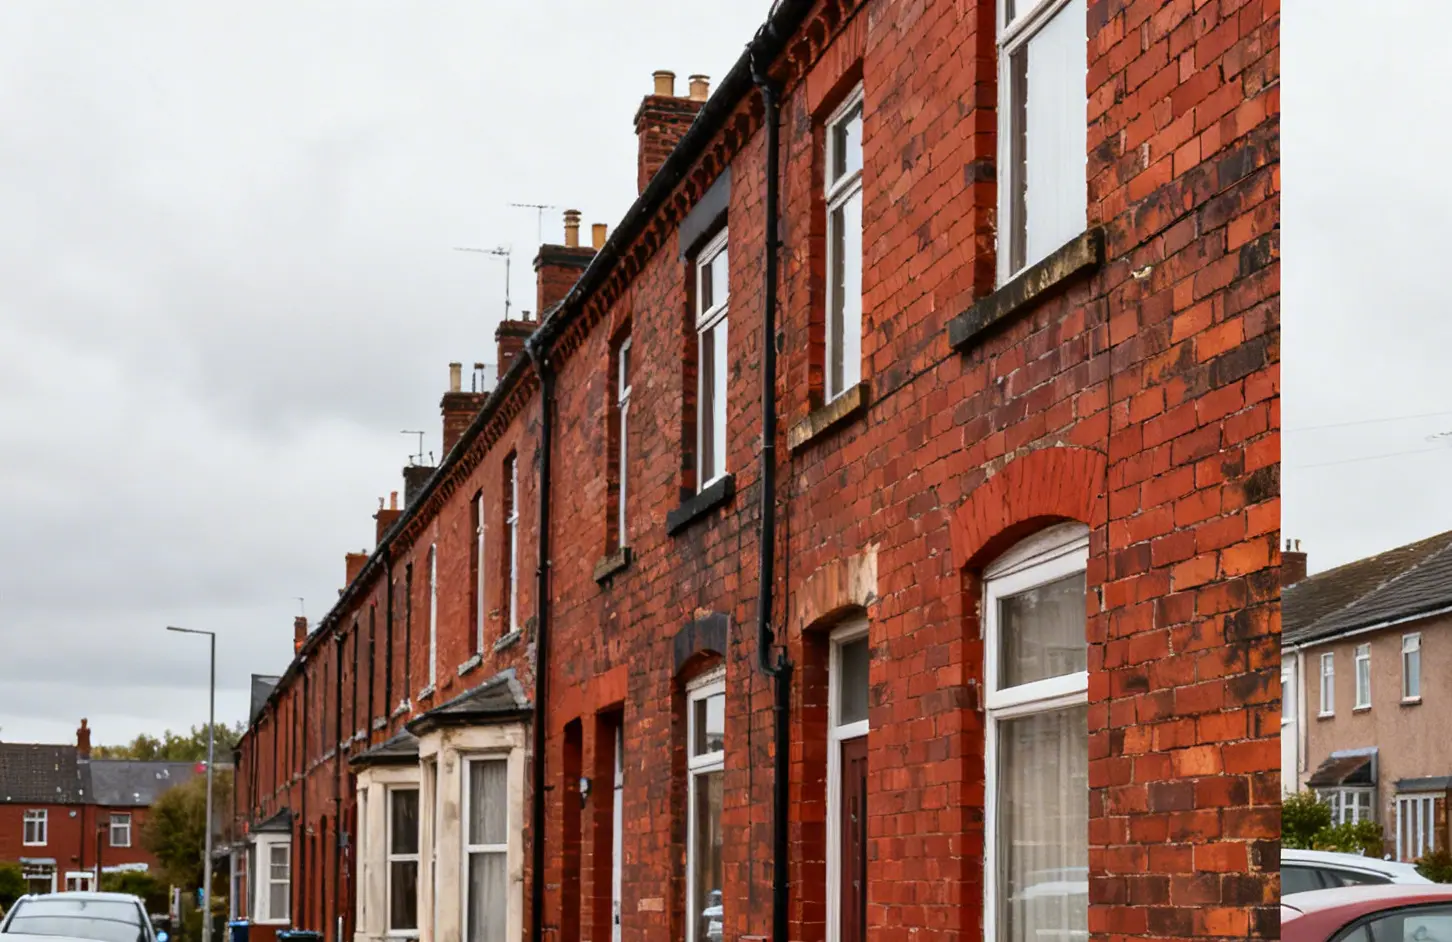
The mathematics of this shift are compelling and rooted in basic investment fundamentals. Northern cities now deliver gross rental yields of 6-8%, compared to London's anaemic 3-4%, whilst purchase prices remain substantially lower. A two-bedroom terrace in Liverpool or Newcastle can be acquired for £120,000-£150,000, generating monthly rents of £700-£900. The same investment capital in Surrey might secure a one-bedroom flat yielding £500-£600 monthly. Professional landlords have recognised this arithmetic advantage, with mortgage lenders reporting that 78% of buy-to-let applications now originate from investors targeting properties north of Birmingham.
Manchester has emerged as the standout beneficiary, capturing approximately 12% of all buy-to-let investment nationally, driven by its expanding tech sector and student population exceeding 100,000. Birmingham follows closely, attracting investment through its Commonwealth Games infrastructure legacy and HS2 connectivity promises. Leeds has seen buy-to-let purchases increase by 340% since 2015, whilst Newcastle's combination of low entry costs and stable rental demand has made it a favourite among portfolio builders seeking multiple property acquisitions. These cities offer the dual advantage of strong tenant demand and realistic purchase prices that satisfy modern lending criteria.
This geographical rebalancing reflects deeper structural changes in both employment patterns and lending standards. The rise of remote working has reduced London's magnetic pull for young professionals, many of whom now establish careers in Manchester, Birmingham, or Leeds whilst paying significantly lower rents. Simultaneously, post-2016 tax changes and stricter affordability assessments have made southern property investments increasingly marginal. The elimination of mortgage interest tax relief and the additional 3% stamp duty surcharge hit hardest in high-value southern markets, where gross yields were already compressed.
Regional rental markets are responding differently to this investment influx. Northern cities are experiencing rental stock expansion and modest yield compression as supply increases, though demand from growing professional populations continues to support rent growth. Conversely, southern markets face a supply squeeze as investment capital flows elsewhere, potentially driving rents higher despite weaker purchase activity. London boroughs outside Zones 1-2 are particularly affected, with some areas reporting 30% fewer new buy-to-let acquisitions compared to pre-2020 levels.
The implications for market participants are profound and enduring. Portfolio landlords will continue prioritising northern acquisitions, where cash flow positive investments remain achievable under current lending conditions. First-time buyers in northern cities face intensified competition from investors, though this has been partially offset by increased new-build supply. For developers, the message is clear: northern rental developments targeting professional tenants command premium investor interest, whilst southern schemes increasingly require overseas capital or institutional backing.
This north-south investment reversal represents more than cyclical market adjustment - it signals a permanent recalibration of UK property investment towards yield-driven strategies. With base rates likely to remain elevated through 2025, southern property investment will continue struggling against the dual headwinds of low yields and high financing costs. Northern markets, by contrast, offer sustainable investment models that align with both lender requirements and investor return expectations, ensuring this geographical shift will accelerate rather than reverse over the coming decade.
Key Takeaways
- Northern England now captures 62% of buy-to-let investment, up from 44% in 2015, driven by superior yield dynamics
- Manchester, Birmingham, and Leeds lead investment flows, offering 6-8% gross yields versus London's 3-4%
- Southern buy-to-let supply is contracting, potentially driving rental inflation despite reduced investor activity
- Portfolio expansion strategies must now focus north of Birmingham to achieve cash-flow positive investments under current lending criteria


