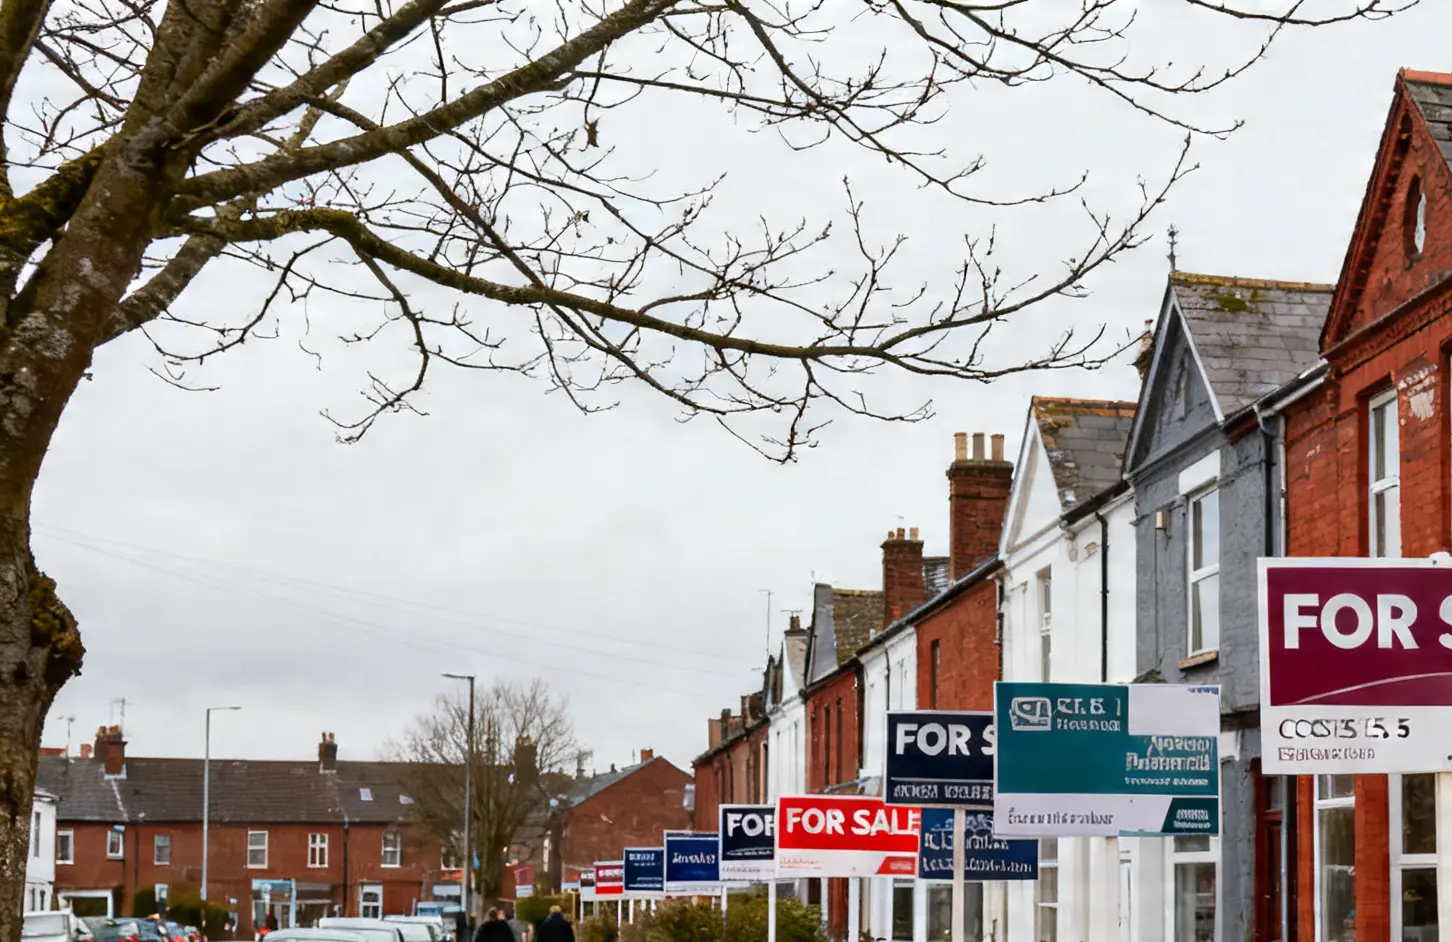
The UK housing market has entered uncharted territory as sellers flood the market whilst buyers retreat, creating the most significant supply-demand imbalance in over a decade. April's modest 0.8% rise in asking prices to £373,971 masks a fundamental shift that will reshape property investment strategies across Britain. With new listings reaching their highest seasonal levels since 2012 and buyer demand trailing 7% behind last year's figures, the post-pandemic seller's market is rapidly transforming into something entirely different.
This supply surge represents a watershed moment for property investors who have grown accustomed to chronic housing shortages driving consistent capital appreciation. The 33% increase in available stock compared to pre-pandemic levels fundamentally alters investment calculations, particularly for buy-to-let landlords operating in traditionally supply-constrained markets like Manchester and Birmingham. These cities, which saw asking prices surge 15-20% during 2021-2022, now face the prospect of extended marketing periods and more aggressive pricing strategies as sellers compete for a shrinking pool of active buyers.
The divergence between asking price growth and underlying market dynamics reveals a seller base still anchored to pandemic-era valuations whilst confronting a dramatically different reality. April's 0.8% monthly increase falls 33% short of the long-term average, yet this modest appreciation occurs against a backdrop of inventory levels not seen since the immediate aftermath of the 2008 financial crisis. Commercial property investors monitoring residential trends will recognise familiar patterns from 2019, when extended supply cycles preceded more substantial price corrections across multiple asset classes.
Regional variations will become increasingly pronounced as this supply-demand rebalancing accelerates through the remainder of 2024. London's prime postcodes, already experiencing inventory increases of 40% year-on-year, face particular pressure as international buyers remain cautious and domestic purchasers struggle with affordability constraints. Conversely, northern cities like Leeds and Newcastle, where absolute price levels remain more accessible, may demonstrate greater resilience despite elevated stock levels. First-time buyers, largely sidelined during the pandemic boom, will find themselves with unprecedented choice and genuine negotiating power for the first time in five years.
The implications for property development pipelines are profound and immediate. Developers with schemes launching in the next 12 months face a market where buyers can afford to wait, compare options extensively, and demand meaningful incentives. This dynamic particularly affects the build-to-rent sector, where operators banking on continued rental growth to justify elevated land costs must recalibrate assumptions about both capital values and rental escalation potential. Sites acquired during the peak market frenzy of 2021-2022 now require fundamental reappraisal of their development economics.
Looking ahead, this supply abundance will persist well into 2025 as homeowners who delayed selling during the mortgage rate spike of 2022-2023 finally enter the market. The combination of elevated inventory and normalising buyer behaviour patterns suggests asking price growth will remain subdued, with realistic prospects of quarterly declines in overheated regional markets. For institutional investors, this environment offers the first genuine buying opportunities since the pandemic began, but requires patience and precision in market timing.
The current market inflection point marks the end of the pandemic-driven housing boom and the beginning of a more balanced, buyer-friendly environment that will define UK property investment for the next two years. Successful investors will adapt quickly to this new paradigm, where due diligence, negotiation skills, and market timing matter more than simply competing for scarce assets. The decade-high supply levels represent not just a cyclical adjustment, but a structural reset that rewards strategic thinking over momentum investing.
Key Takeaways
- Inventory levels at decade highs create first genuine buyer's market since 2019, fundamentally shifting negotiation dynamics across all property sectors
- Regional markets face divergent outcomes: London prime property and pandemic boom towns most vulnerable to extended correction cycles
- Development schemes launching in next 12 months require immediate strategy revision as buyers gain unprecedented choice and pricing power
- Buy-to-let investors should prioritise northern cities with accessible pricing over southern markets facing affordability constraints and oversupply


