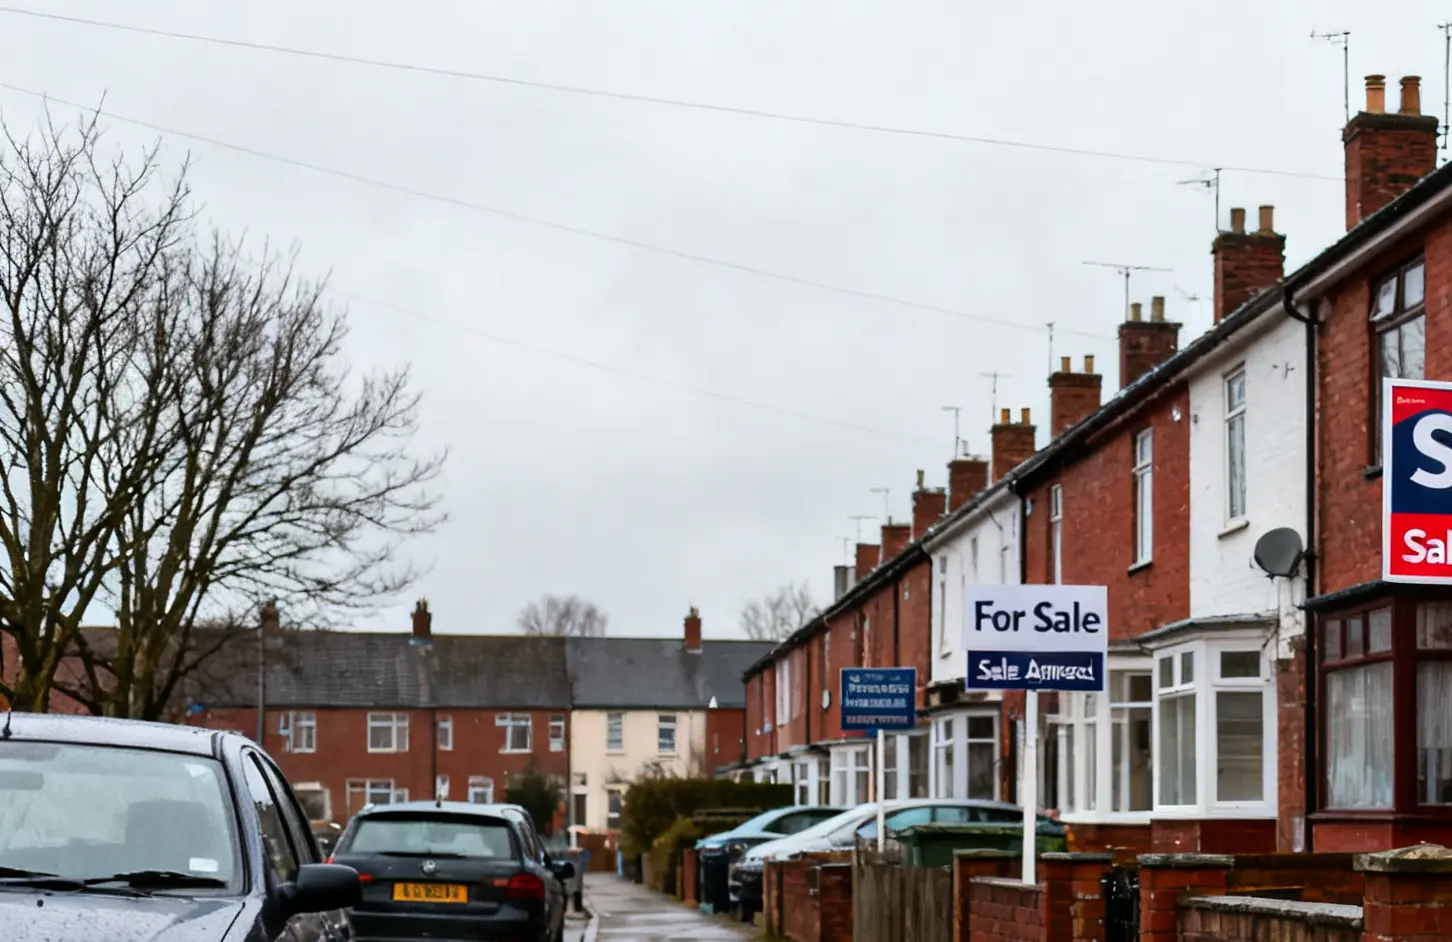
The UK property market faces an intensifying supply squeeze after nearly one in four homeowners who planned to sell in January have abandoned their intentions, creating a pipeline shortage that will amplify pricing pressures across both prime and secondary markets. GetAgent's survey of 1,011 property vendors reveals that 24% have shelved moving plans entirely, removing crucial stock from an already constrained market where inventory levels remain 15-20% below pre-pandemic norms.
This vendor exodus stems from a toxic combination of mortgage rate uncertainty and valuation concerns that have paralysed decision-making among move-up buyers who represent the backbone of market liquidity. Properties priced between £300,000-£600,000 across Manchester, Birmingham, and Leeds - traditionally the most active trading segment - are experiencing particularly acute withdrawal rates as sellers refuse to accept price reductions whilst simultaneously hesitating to commit to higher borrowing costs on their next purchase. The phenomenon creates a self-reinforcing cycle where reduced stock levels support current valuations, yet transaction volumes collapse as the market becomes increasingly illiquid.
Regional markets are experiencing divergent impacts from this supply withdrawal, with London's prime boroughs actually benefiting from scarcity-driven price support despite broader economic headwinds. Areas such as Surrey and the Home Counties, where the £500,000-£1.2 million segment dominates, face the most severe disruption as equity-rich homeowners delay upsizing decisions. Conversely, Liverpool and Newcastle's sub-£250,000 markets continue functioning effectively, supported by first-time buyer activity and limited exposure to higher-rate mortgage products that have deterred vendors elsewhere.
Buy-to-let investors face a critical window of opportunity as reduced stock levels coincide with persistent rental demand, particularly in university cities and commuter towns where yield compression had previously deterred investment. The 24% vendor withdrawal rate suggests achievable purchase prices may stabilise or even increase modestly, yet rental growth trajectories remain robust enough to support investment returns for those securing properties at current pricing levels. Professional landlords with cash positions should prioritise Birmingham and Manchester suburbs where rental demand exceeds supply by margins approaching 3:1.
First-time buyers confront an increasingly challenging landscape where the traditional benefit of market downturns - expanded choice and negotiating power - has been neutralised by supply constraints. Properties suitable for FTB budgets below £250,000 were already scarce in southern England, and vendor withdrawals have reduced available stock by an estimated 20-30% in key commuter locations within 60 minutes of London. This demographic now faces a stark choice between accepting higher prices for limited options or extending geographical searches to traditionally less favoured locations where transport links constrain future resale potential.
The commercial implications extend beyond residential markets, as reduced transaction volumes directly impact estate agents, conveyancers, and mortgage brokers whose revenue streams depend on completed deals rather than market valuations. Major estate agency chains are likely to report significantly reduced commission income for Q1 2024, forcing branch consolidations and staffing adjustments that will further constrain market capacity when vendor confidence eventually returns.
This supply shock will persist through the first half of 2024, with meaningful stock level recovery unlikely before mortgage rate clarity emerges and vendor confidence stabilises. The fundamental imbalance between housing demand and available inventory ensures that any resumption of normal selling patterns will trigger rapid price acceleration, particularly in supply-constrained regions where population growth continues outpacing housing delivery. Professional investors who can navigate the current illiquid environment position themselves advantageously for the inevitable supply-demand rebalancing that will define the UK property market's next growth phase.
Key Takeaways
- Supply shortage intensifying as 24% vendor withdrawal removes critical inventory from already constrained markets, supporting price stability despite economic headwinds
- Regional divergence accelerating with London and Home Counties benefiting from scarcity whilst northern cities maintain transaction volumes through lower price points
- Buy-to-let investors face optimal entry window in Birmingham and Manchester suburbs where rental demand significantly exceeds reduced available stock
- First-time buyers must expand geographical searches as suitable properties below £250,000 become increasingly scarce in southern England commuter locations


