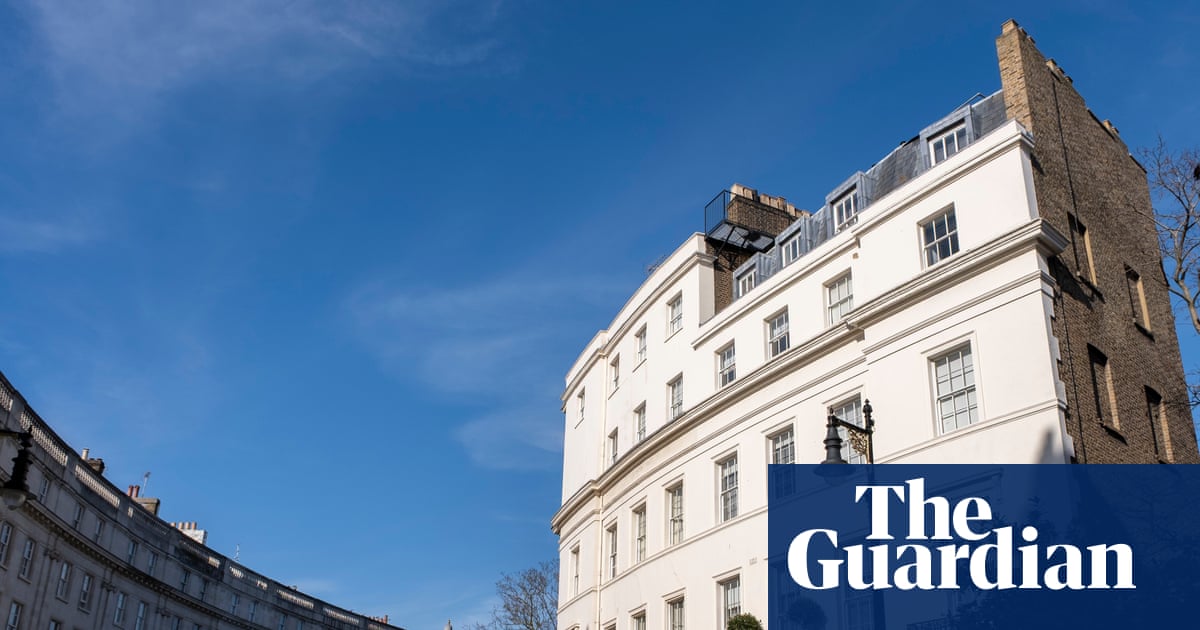
Prime central London's property market has suffered a fresh blow, with prices across the capital's most exclusive postcodes falling 5% in the third quarter of 2026, as PropertyWire reported. The figures reveal a market under sustained pressure: eight out of ten properties in prime central London are now selling below their asking price, while homes in Mayfair, Belgravia and Knightsbridge are changing hands at an average discount of 10% to the price originally sought by sellers.
For professional investors and developers, this is not a minor correction to be shrugged off. Prime central London has long served as a bellwether for sentiment at the top of the UK market, a segment historically insulated from the affordability pressures facing ordinary buyers but highly sensitive to global capital flows, currency movements and tax policy. A 5% quarterly fall, combined with the scale of discounting now evident, signals that sellers are being forced to recalibrate expectations that had, until recently, remained stubbornly optimistic. When eight in ten transactions complete below asking, it is no longer a case of a few overpriced listings lingering on the market; it points to a structural repricing across the board.
The scale of the discounts in Mayfair, Belgravia and Knightsbridge is particularly telling. These postcodes represent the most liquid and internationally watched corners of the London market, traditionally the first to recover when global wealth flows back into UK real estate and the last to show weakness when demand softens. A 10% average discount in this tier suggests vendors are either overestimating value based on historic peak pricing, or are facing genuine difficulty attracting the pool of ultra-high-net-worth buyers who once competed aggressively for trophy assets in these streets. Either way, the gap between asking price and sale price has become too wide to ignore.
The implications ripple outward well beyond the prime core. For buy-to-let landlords operating in prime and super-prime London, softer capital values complicate exit strategies and may dampen appetite for further acquisitions in the short term, even where rental demand remains firm. Commercial investors eyeing residential-led mixed-use schemes in central London will need to stress-test valuations more conservatively, particularly where financing was structured around pricing assumptions now looking dated. Developers with stock in the pipeline across Mayfair and Knightsbridge face a harder sell: marketing suites built around aspirational asking prices will need to adjust, or risk extended void periods and mounting holding costs.
First-time buyers and mainstream investors in cities such as Manchester, Birmingham, Leeds, Liverpool and Newcastle are unlikely to feel direct spillover from this specific correction, given how distinct the prime central London market is from regional housing dynamics. However, the broader lesson for the wider UK market is instructive: even the most resilient, globally-oriented segment of British property is not immune to repricing when buyer confidence wavers. Investors who have assumed that prime London values only move in one direction should treat this quarter's figures as a reminder that liquidity and pricing power can shift quickly, even in markets with a long track record of capital preservation.
Looking ahead to the next six to twelve months, PropertyNews analysis suggests sellers in prime central London will need to adjust pricing strategies more realistically if the current pace of discounting persists, particularly in Mayfair, Belgravia and Knightsbridge where the gap between expectation and achieved price is widest. Buyers with patience and available capital may find this an opportune moment to negotiate hard, given the clear evidence that the majority of vendors are already conceding ground. For the broader investment community, the message is one of caution rather than alarm: this is a segment-specific correction rooted in pricing discipline, not necessarily a signal of wider market distress, but one that merits close monitoring as the final quarter of the year unfolds.
Key Takeaways
- Prime central London prices fell 5% in Q3 2026, with 80% of properties selling below asking price, as reported by PropertyWire.
- Mayfair, Belgravia and Knightsbridge recorded average discounts of 10% against asking prices, among the sharpest in the prime market.
- Developers and sellers in these postcodes should recalibrate pricing expectations rather than hold out for historic peak valuations.
- Buyers with capital to deploy may find increased negotiating leverage in prime London over the coming months, while regional UK markets remain largely insulated from this specific correction.