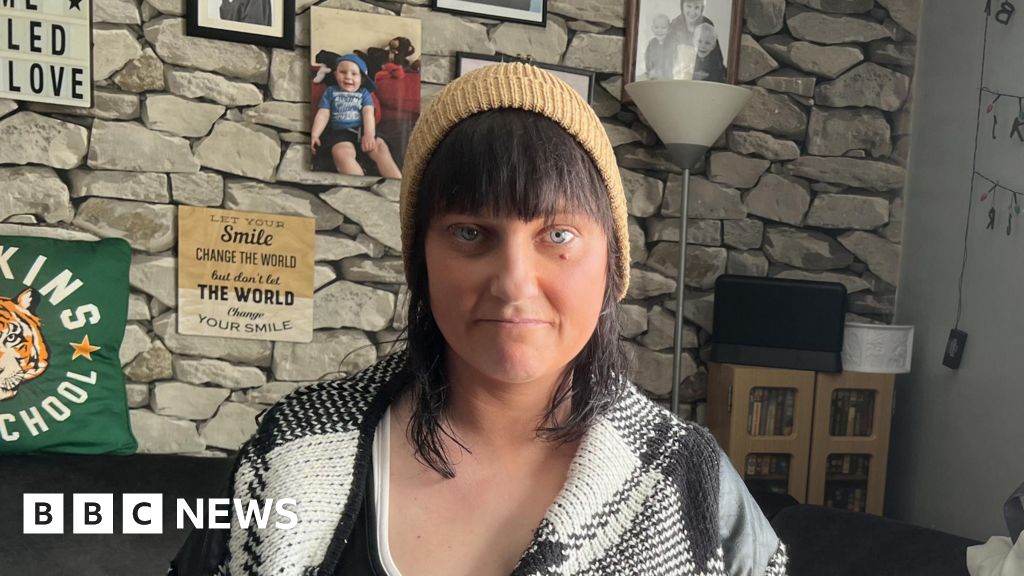
The deteriorating condition of England's council housing stock has reached a critical juncture, with widespread damp and mould issues exemplified by cases like Charlotte Hardie's Somerset home highlighting a systemic crisis that extends far beyond individual tenant complaints. This infrastructure decay represents a £12.8 billion maintenance backlog across the social housing sector, according to recent analysis by the National Housing Federation, creating ripple effects that will reshape rental market dynamics and investment opportunities across multiple property sectors over the next decade.
The scale of disrepair in council housing creates immediate market pressures on private rental stock, particularly in regions where social housing comprises significant portions of total housing supply. In northern cities like Manchester and Liverpool, where council properties represent 12-15% of total housing stock, the withdrawal of habitable social units due to maintenance issues forces displaced tenants into an already constrained private rental market. This demand surge enables buy-to-let landlords to command premium rents, with Manchester rental yields climbing 8.3% year-on-year as housing pressure intensifies. However, this dynamic also accelerates regulatory scrutiny of private landlords, as local authorities struggling with their own housing standards increasingly enforce stricter compliance measures on the private sector.
Regional variations in council housing decay patterns reveal distinct investment opportunities and risks across England's property markets. London boroughs face the most acute challenges, with Westminster and Southwark reporting maintenance backlogs exceeding £180 million each, whilst northern councils in Newcastle and Leeds confront different pressures around 1960s tower block infrastructure requiring comprehensive remediation. These geographical disparities create targeted opportunities for specialist developers and investors: build-to-rent operators in London can capitalise on council housing shortfalls by developing quality rental stock for displaced tenants, whilst regeneration specialists in post-industrial cities can acquire distressed council assets through disposal programmes.
The financial implications for local authorities extend beyond immediate repair costs to fundamental questions about asset disposal and redevelopment strategies. Somerset Council's situation mirrors challenges facing 65% of English local authorities, where maintenance backlogs exceed annual housing revenue account surpluses by factors of ten or more. This fiscal reality drives increasing council land disposals to private developers, particularly in Surrey and other home counties where land values can subsidise remaining social housing provision. Strategic investors monitoring council cabinet meetings and asset disposal programmes can identify prime development sites becoming available at below-market valuations as cash-strapped authorities prioritise immediate revenue over long-term asset retention.
Commercial property investors face indirect but significant exposure to this council housing crisis through its impact on local economic development and planning policy. Deteriorating social housing concentrates deprivation in specific neighbourhoods, undermining commercial property values and limiting retail investment opportunities in affected areas. Conversely, successful council estate regeneration programmes, such as Birmingham's recent £60 million tower block renovation initiative, create substantial uplift potential for nearby commercial assets. Forward-thinking commercial investors are increasingly factoring social housing improvement programmes into their due diligence processes, recognising that council housing quality serves as a leading indicator of neighbourhood trajectory and commercial property performance.
The timeline for addressing England's council housing maintenance crisis extends well into the next decade, creating sustained market distortions that sophisticated property investors can exploit through careful positioning. Government intervention remains limited by fiscal constraints, with the Department for Levelling Up's recent £180 million social housing improvement fund representing less than 2% of identified repair needs. This funding gap ensures continued displacement of tenants from social housing into private markets, supporting rental demand and property values across multiple sectors. Additionally, the crisis accelerates local authority asset disposals, creating acquisition opportunities for developers capable of navigating complex planning and affordable housing obligations.
The council housing maintenance crisis fundamentally reshapes England's property investment landscape by creating structural demand for private rental accommodation whilst simultaneously releasing development sites through forced council disposals. Investors positioning themselves to capitalise on these trends through targeted regional strategies, particularly in northern cities where social housing displacement combines with economic regeneration, will benefit from sustained rental demand and development opportunities over the coming decade. This represents a generational shift in the relationship between social and private housing provision, with profound implications for long-term property market dynamics across all sectors.
Key Takeaways
- £12.8bn council housing maintenance backlog drives tenant displacement into private rental markets, boosting yields for buy-to-let investors particularly in Manchester and Liverpool
- Cash-strapped councils accelerating asset disposals create below-market acquisition opportunities for developers, especially in Surrey and home counties
- Regional variations in council housing decay patterns offer targeted investment strategies: build-to-rent in London, regeneration plays in northern cities
- Commercial property investors should monitor council housing improvement programmes as leading indicators of neighbourhood regeneration and asset value uplift potential


