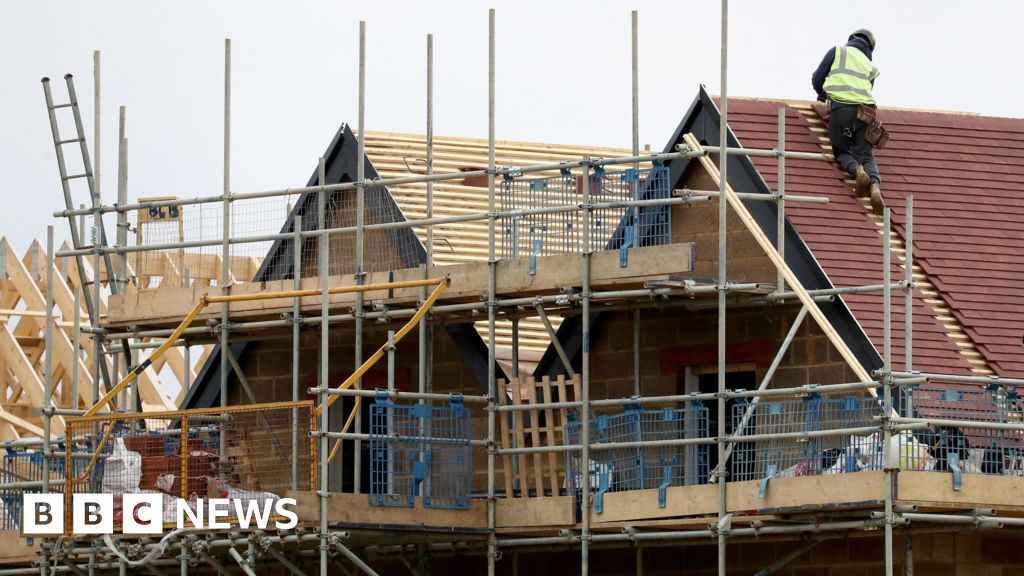
A major local authority's commitment to deliver 580 new council homes over the next six years represents far more than a single housing project - it signals a fundamental shift in how Britain addresses its housing crisis and creates substantial implications for private property investors across multiple asset classes. This programme, emphasising energy efficiency alongside traditional social housing provision, reflects growing municipal confidence in direct development at a time when private housebuilders face mounting pressure from interest rates and construction costs.
The scale and timeline of this initiative - averaging nearly 100 homes annually - positions the local authority as a significant market participant that will compete directly with private developers for land, labour, and materials. Current data suggests council house completions nationally remain below 2,000 units annually, making programmes of this magnitude particularly noteworthy. The emphasis on energy efficiency aligns with emerging regulatory frameworks that will likely mandate similar standards across all new builds, potentially driving construction costs up by 8-12% industry-wide as thermal performance requirements tighten.
Regional property markets will experience varying degrees of disruption depending on local authority appetite for similar programmes. Northern cities including Manchester, Leeds, and Liverpool possess both the political will and available land to replicate such initiatives, potentially adding thousands of units to local housing supply over the medium term. This increased supply could moderate rental growth in these markets, particularly affecting buy-to-let investors targeting lower-income demographics who may find their tenant base migrating to superior council accommodation at competitive rents.
Private developers face a complex landscape as local authorities re-enter the housing market with significant resources and longer investment horizons. While increased competition for sites appears inevitable, opportunities emerge in partnership arrangements and specialist services. Many councils lack the technical expertise for large-scale development, creating demand for private sector involvement in project management, construction, and ongoing maintenance. Forward-thinking developers are already positioning themselves as preferred partners for local authorities seeking to accelerate delivery timelines.
The commercial property sector will benefit substantially from this council housing renaissance, particularly in industrial and logistics. Increased construction activity drives demand for building materials storage, plant hire facilities, and worker accommodation in surrounding areas. Newcastle and Birmingham, both with active council development programmes, have seen industrial rents rise 15-20% in districts adjacent to major housing sites over the past 18 months.
Financial implications extend beyond immediate construction impacts. Local authorities issuing bonds or securing borrowing for housing programmes create new dynamics in municipal debt markets, potentially affecting broader infrastructure investment capacity. The Public Works Loan Board's recent rate adjustments make such borrowing more expensive, suggesting councils pursuing ambitious programmes possess strong conviction about long-term housing demand and rental income potential.
This council housing revival fundamentally alters Britain's property investment landscape by introducing a well-funded, patient capital competitor focused on long-term asset accumulation rather than profit maximisation. Private investors must adapt strategies accordingly, focusing on market segments where councils cannot or will not compete - luxury developments, specialist accommodation, and commercial property serving the expanded construction sector. The next 12 months will determine whether this represents an isolated initiative or the vanguard of a broader municipal housing movement that reshapes regional property dynamics nationwide.
Key Takeaways
- Council housing programmes will increase construction sector demand, benefiting industrial property and logistics facilities in development areas
- Buy-to-let investors should reassess exposure to lower-income rental markets where new council housing may reduce tenant demand
- Partnership opportunities with local authorities will expand for developers offering project management and construction expertise
- Regional markets in Manchester, Leeds, and Liverpool face similar supply increases as councils replicate successful housing programmes


